Aluminum is becoming an increasingly strategic metal, and the economics of producing it in the United States have never been more attractive.
That’s why we first added CENX to our portfolio in May 2026. However, our timing wasn’t perfect, as aluminum prices started pulling back in June.
That said, aluminum prices have been recovering since July, but this has yet to translate into a higher share price for Century Aluminum (CENX).
In the meantime, the investment case for CENX has become much more compelling.
1) The U.S. Needs More Domestic Aluminum Production: The U.S. will need more domestic aluminum production to meet future demand, as it can no longer rely on China or Indonesia for new supply. CENX is well-positioned to benefit.
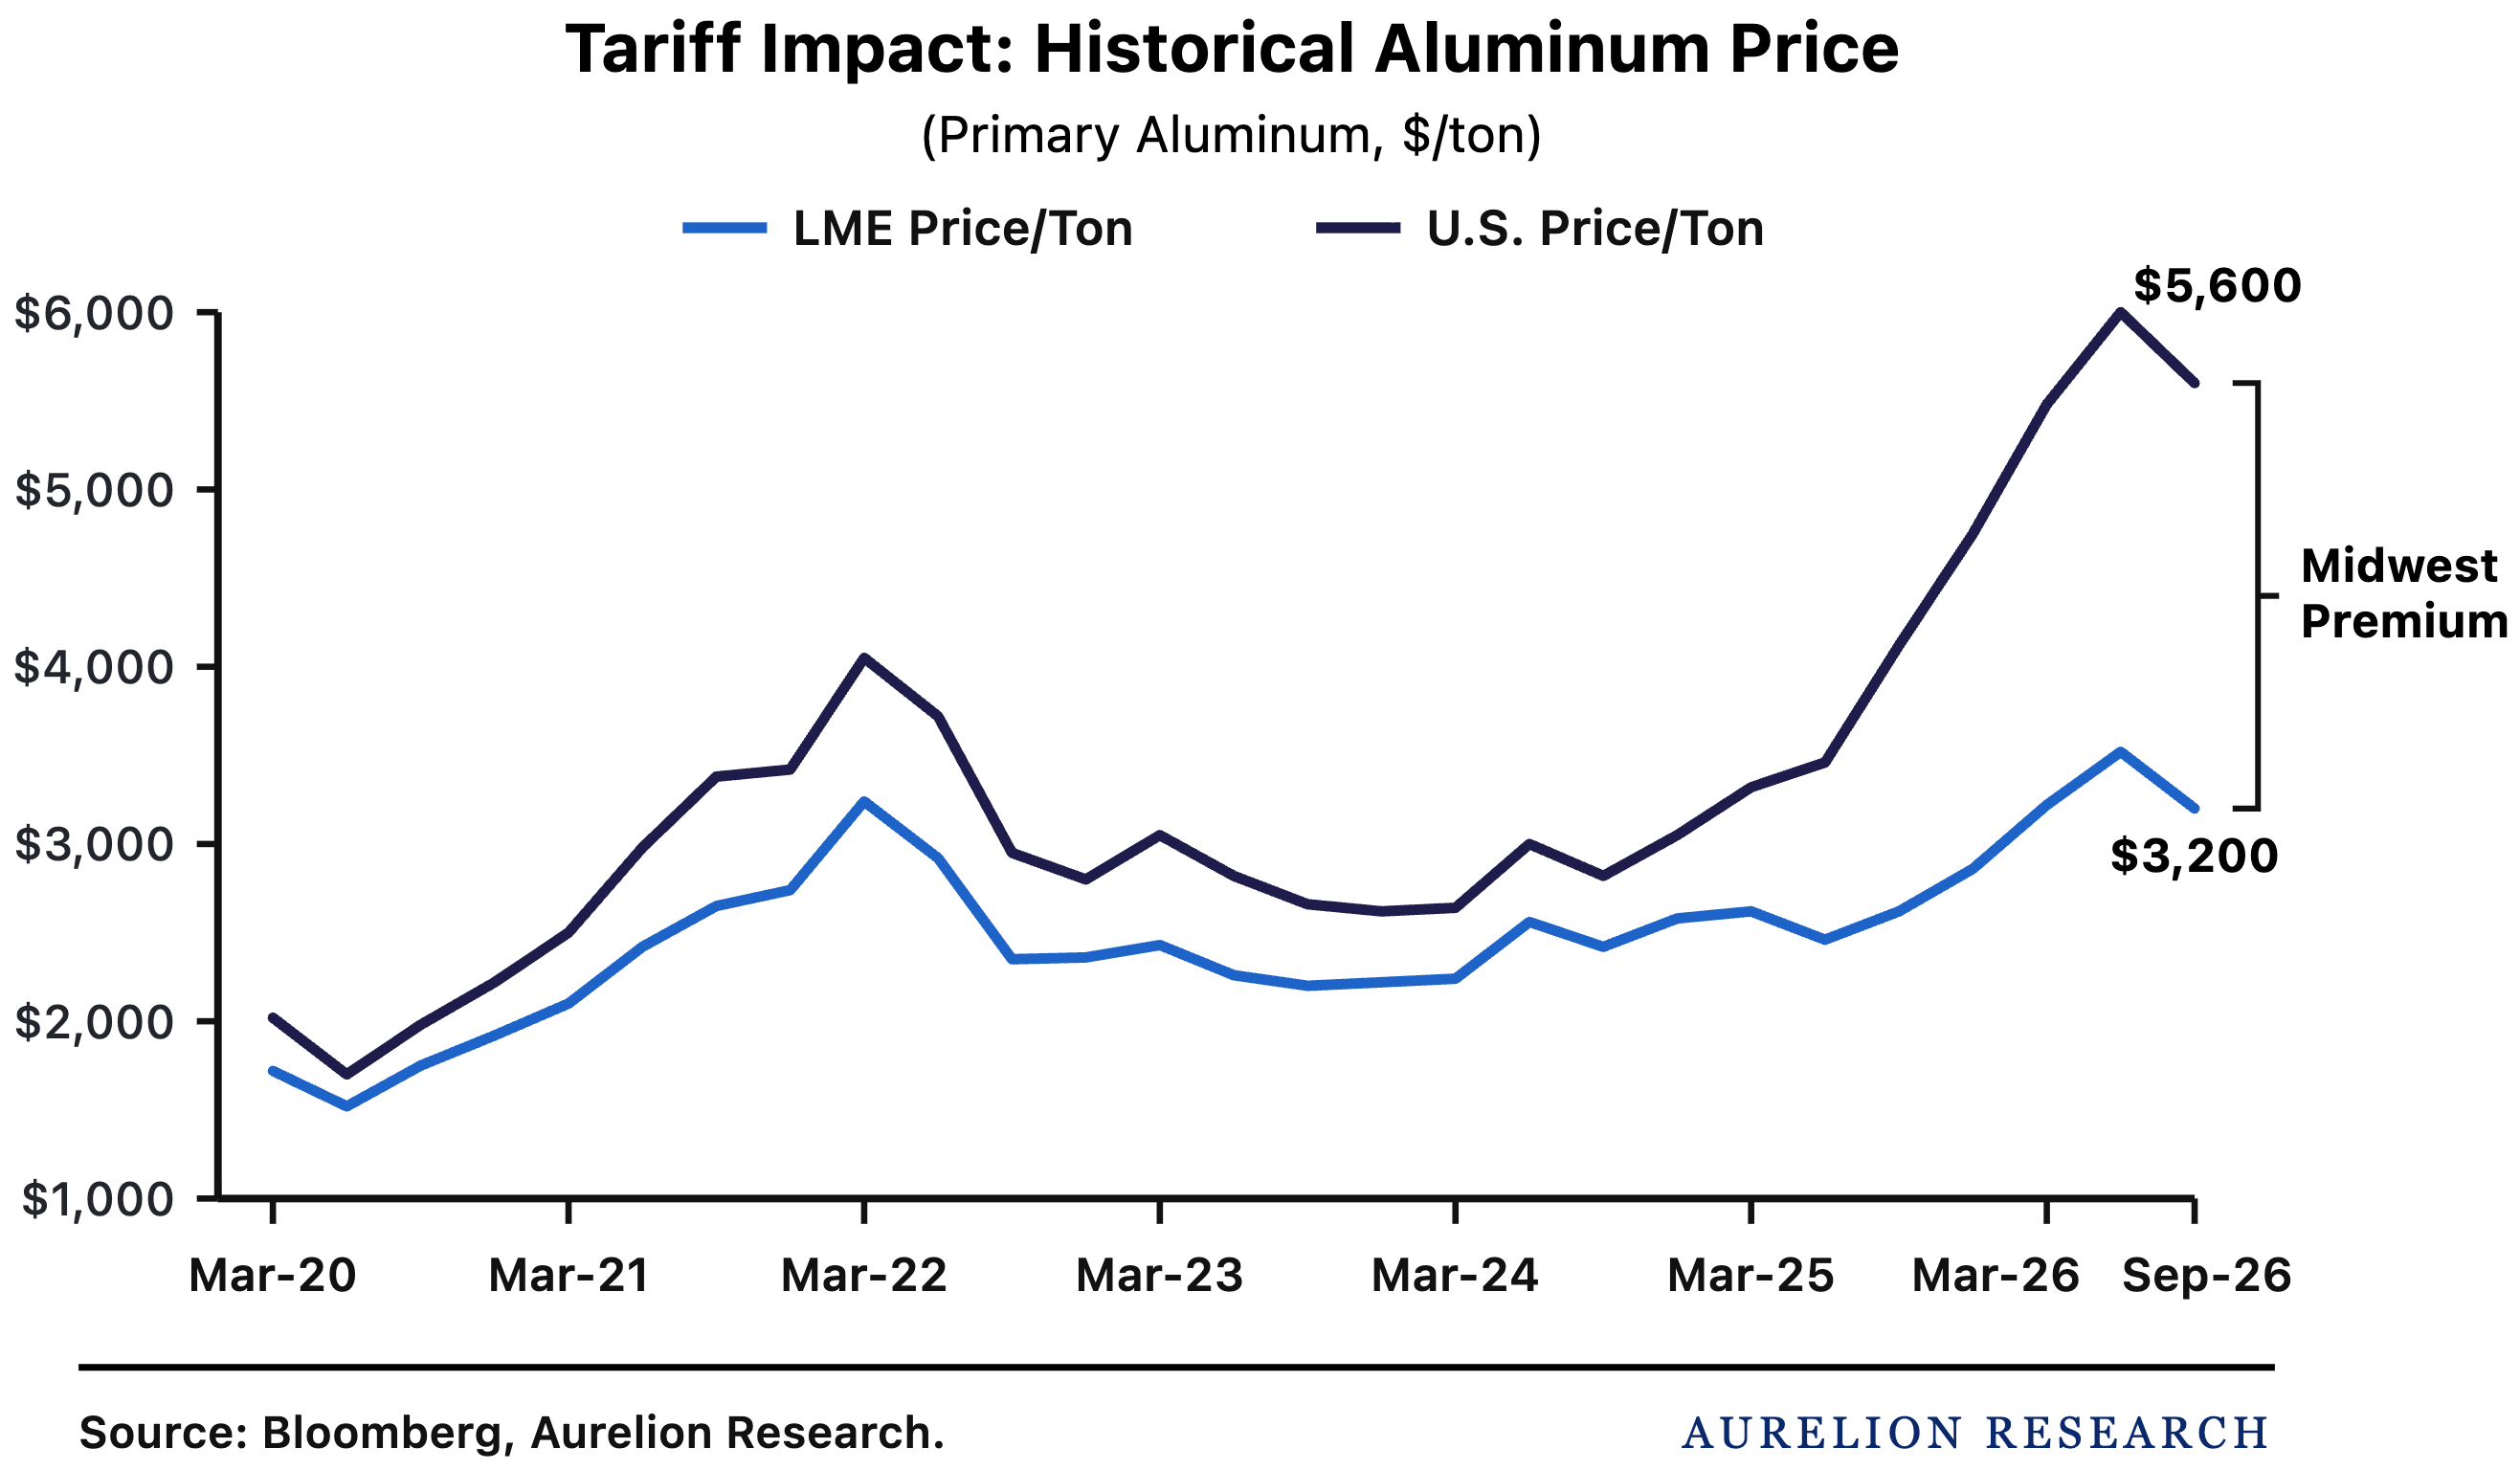
2) Tariff Risks Are Overblown and Already Priced In: We expect U.S. tariffs to remain in place as long as Trump is in office. While they could be reduced from 50% to 25%, we believe this is already priced into CENX’s share price.
3) The Midwest Premium Gives CENX a Pricing Advantage: Tariffs allow U.S. producers like CENX to charge more for their aluminum. This additional cost, known as the Midwest Premium, is a key driver of CENX’s free cash flow.
Further, we argue the company is extremely cheap relative to the cash it will generate. Its operations generates massive amounts of cash, and government tax credits plus the sale of its data center stake add on top.
By Q1 2029, we calculate CENX will have generated enough cash to buy itself outright. Today, the stock trades at just ~3x FY2027 free cash flow.
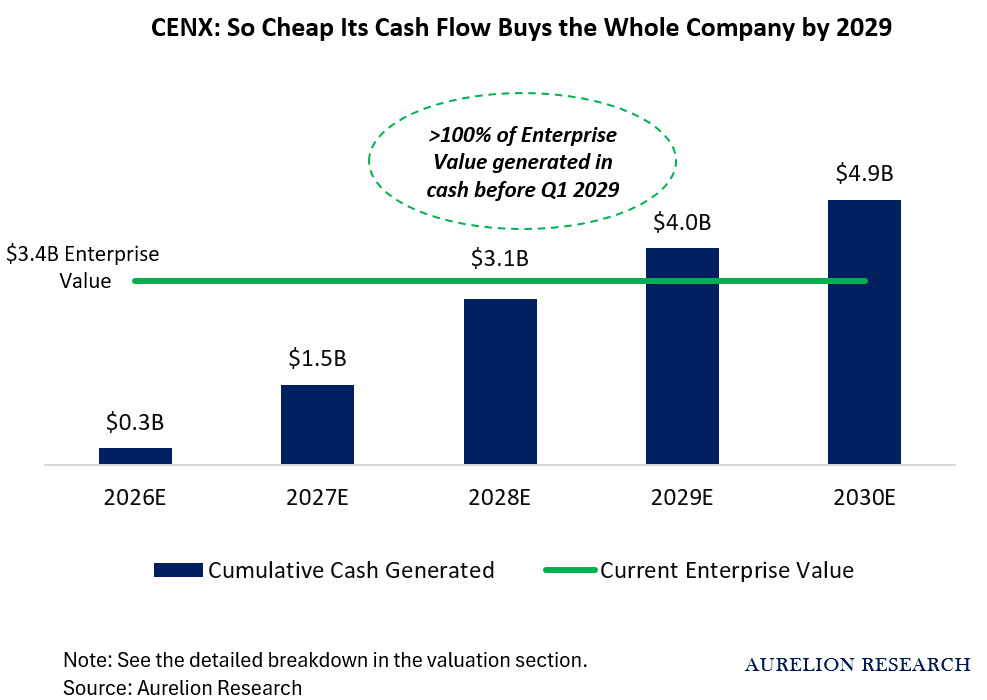
If cash generation continues, something has to give: either the market re-rates the stock, or a buyer steps in.
In this piece, we go into detail on why we are reiterating our conviction in CENX, where the aluminum market is heading and our take on aluminum prices.
At today’s valuation, we believe the market is underestimating what this business can earn, leaving significant upside for the stock.
Table of Contents
1. Where Is the Aluminum Market Heading?
2. Reiterating Conviction in CENX
3. Business Overview
4. Our View on Aluminum Prices
5. Valuation & Price Target
6. What Could Go Wrong
7. Our Final Thoughts
Aluminum Terms Glossary
Smelter: Facility that converts alumina into primary aluminum.
Foundry: Facility that melts and casts aluminum into products.
Midwest Premium: Extra cost for aluminum delivered to the U.S. Midwest.
LME Price: Global benchmark price for aluminum.
Alumina: Refined material used to produce primary aluminum.
Primary Aluminum: Aluminum produced directly from alumina.
1. Where Is the Aluminum Market Heading?
The Iran war has made aluminum one of the metals most exposed to supply disruptions. According to Bloomberg, global supply is expected to fall 1.1% to 73.2 million tons in 2026, with Gulf production down nearly 30% through July.
This could push the global deficit to a record 2.2 million tons.
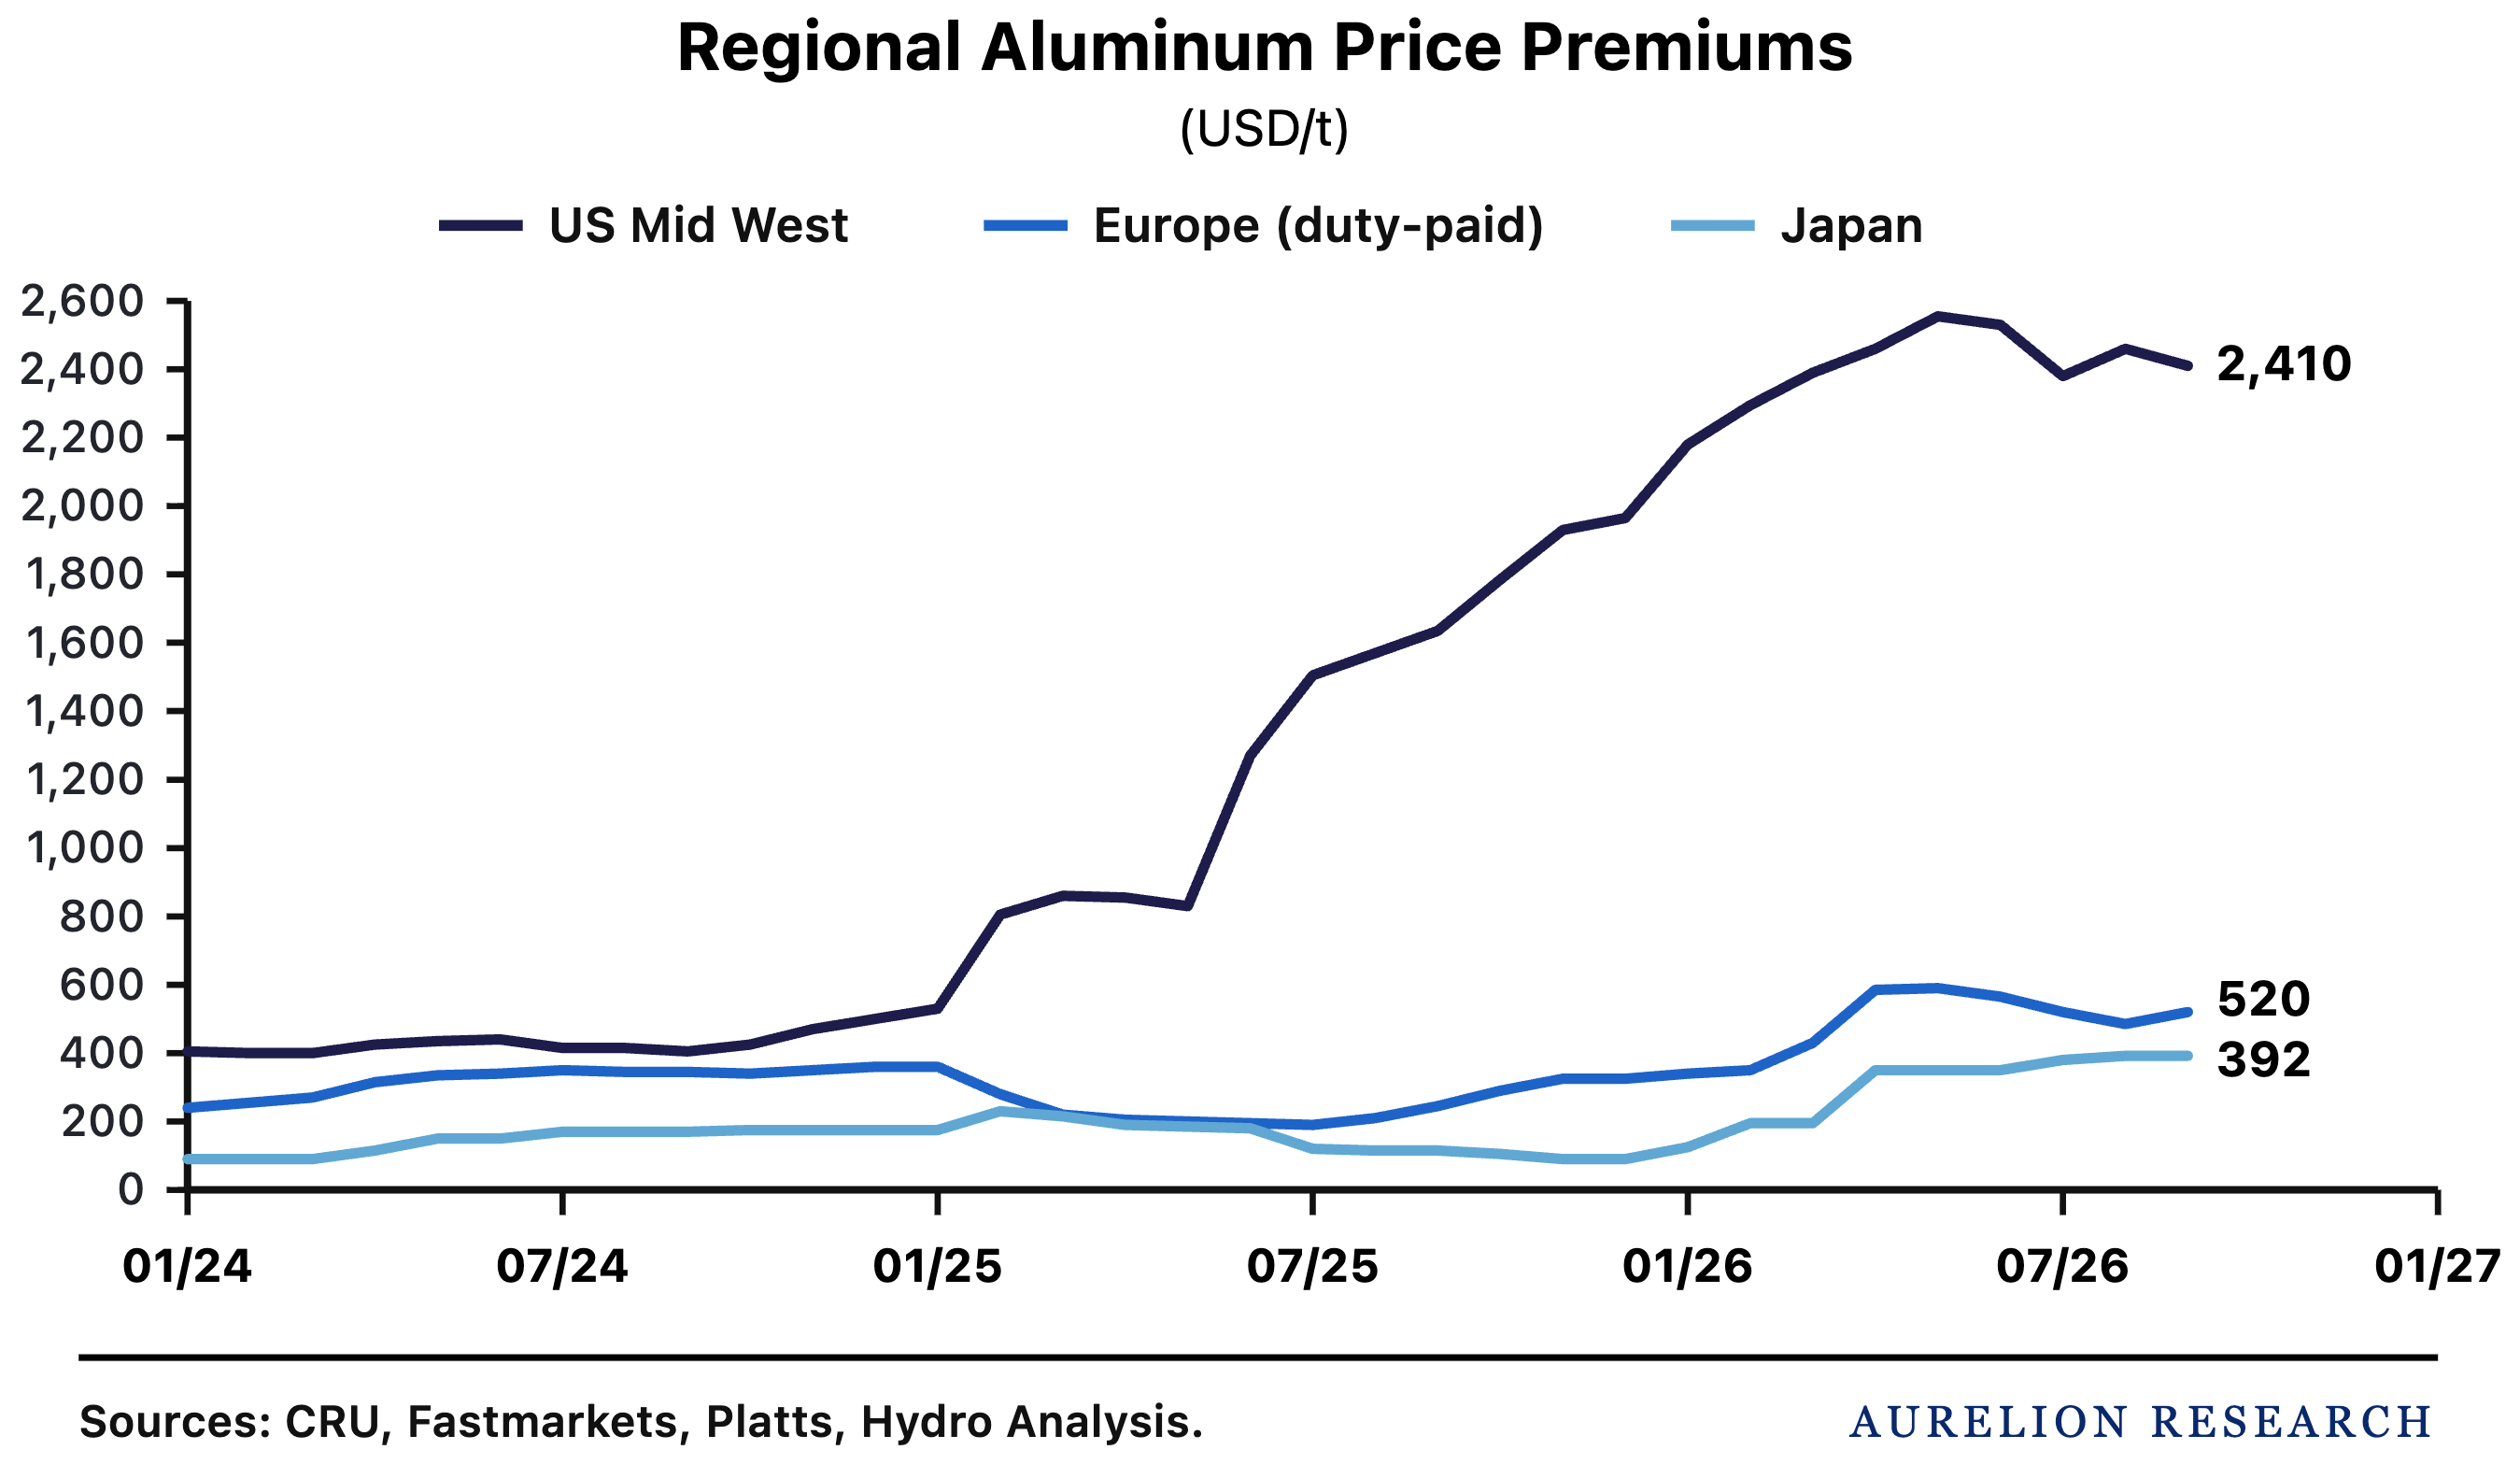
Demand growth is also slowing, from 2.8% in 2025 to 1.3% in 2026, mainly due to weaker growth in China. At the same time, aluminum premiums have increased across major markets. The U.S. Midwest premium has risen with higher tariffs, while Rotterdam and Japan premiums have increased since the war began.
Several factors could limit new aluminum supply. Indonesia is increasing production, while Middle Eastern smelters are expected to restart. However, we think the market is too optimistic about how quickly this supply will return. Geopolitical risks and higher production costs could delay the recovery.
Global Aluminum Inventories Continue to Decline
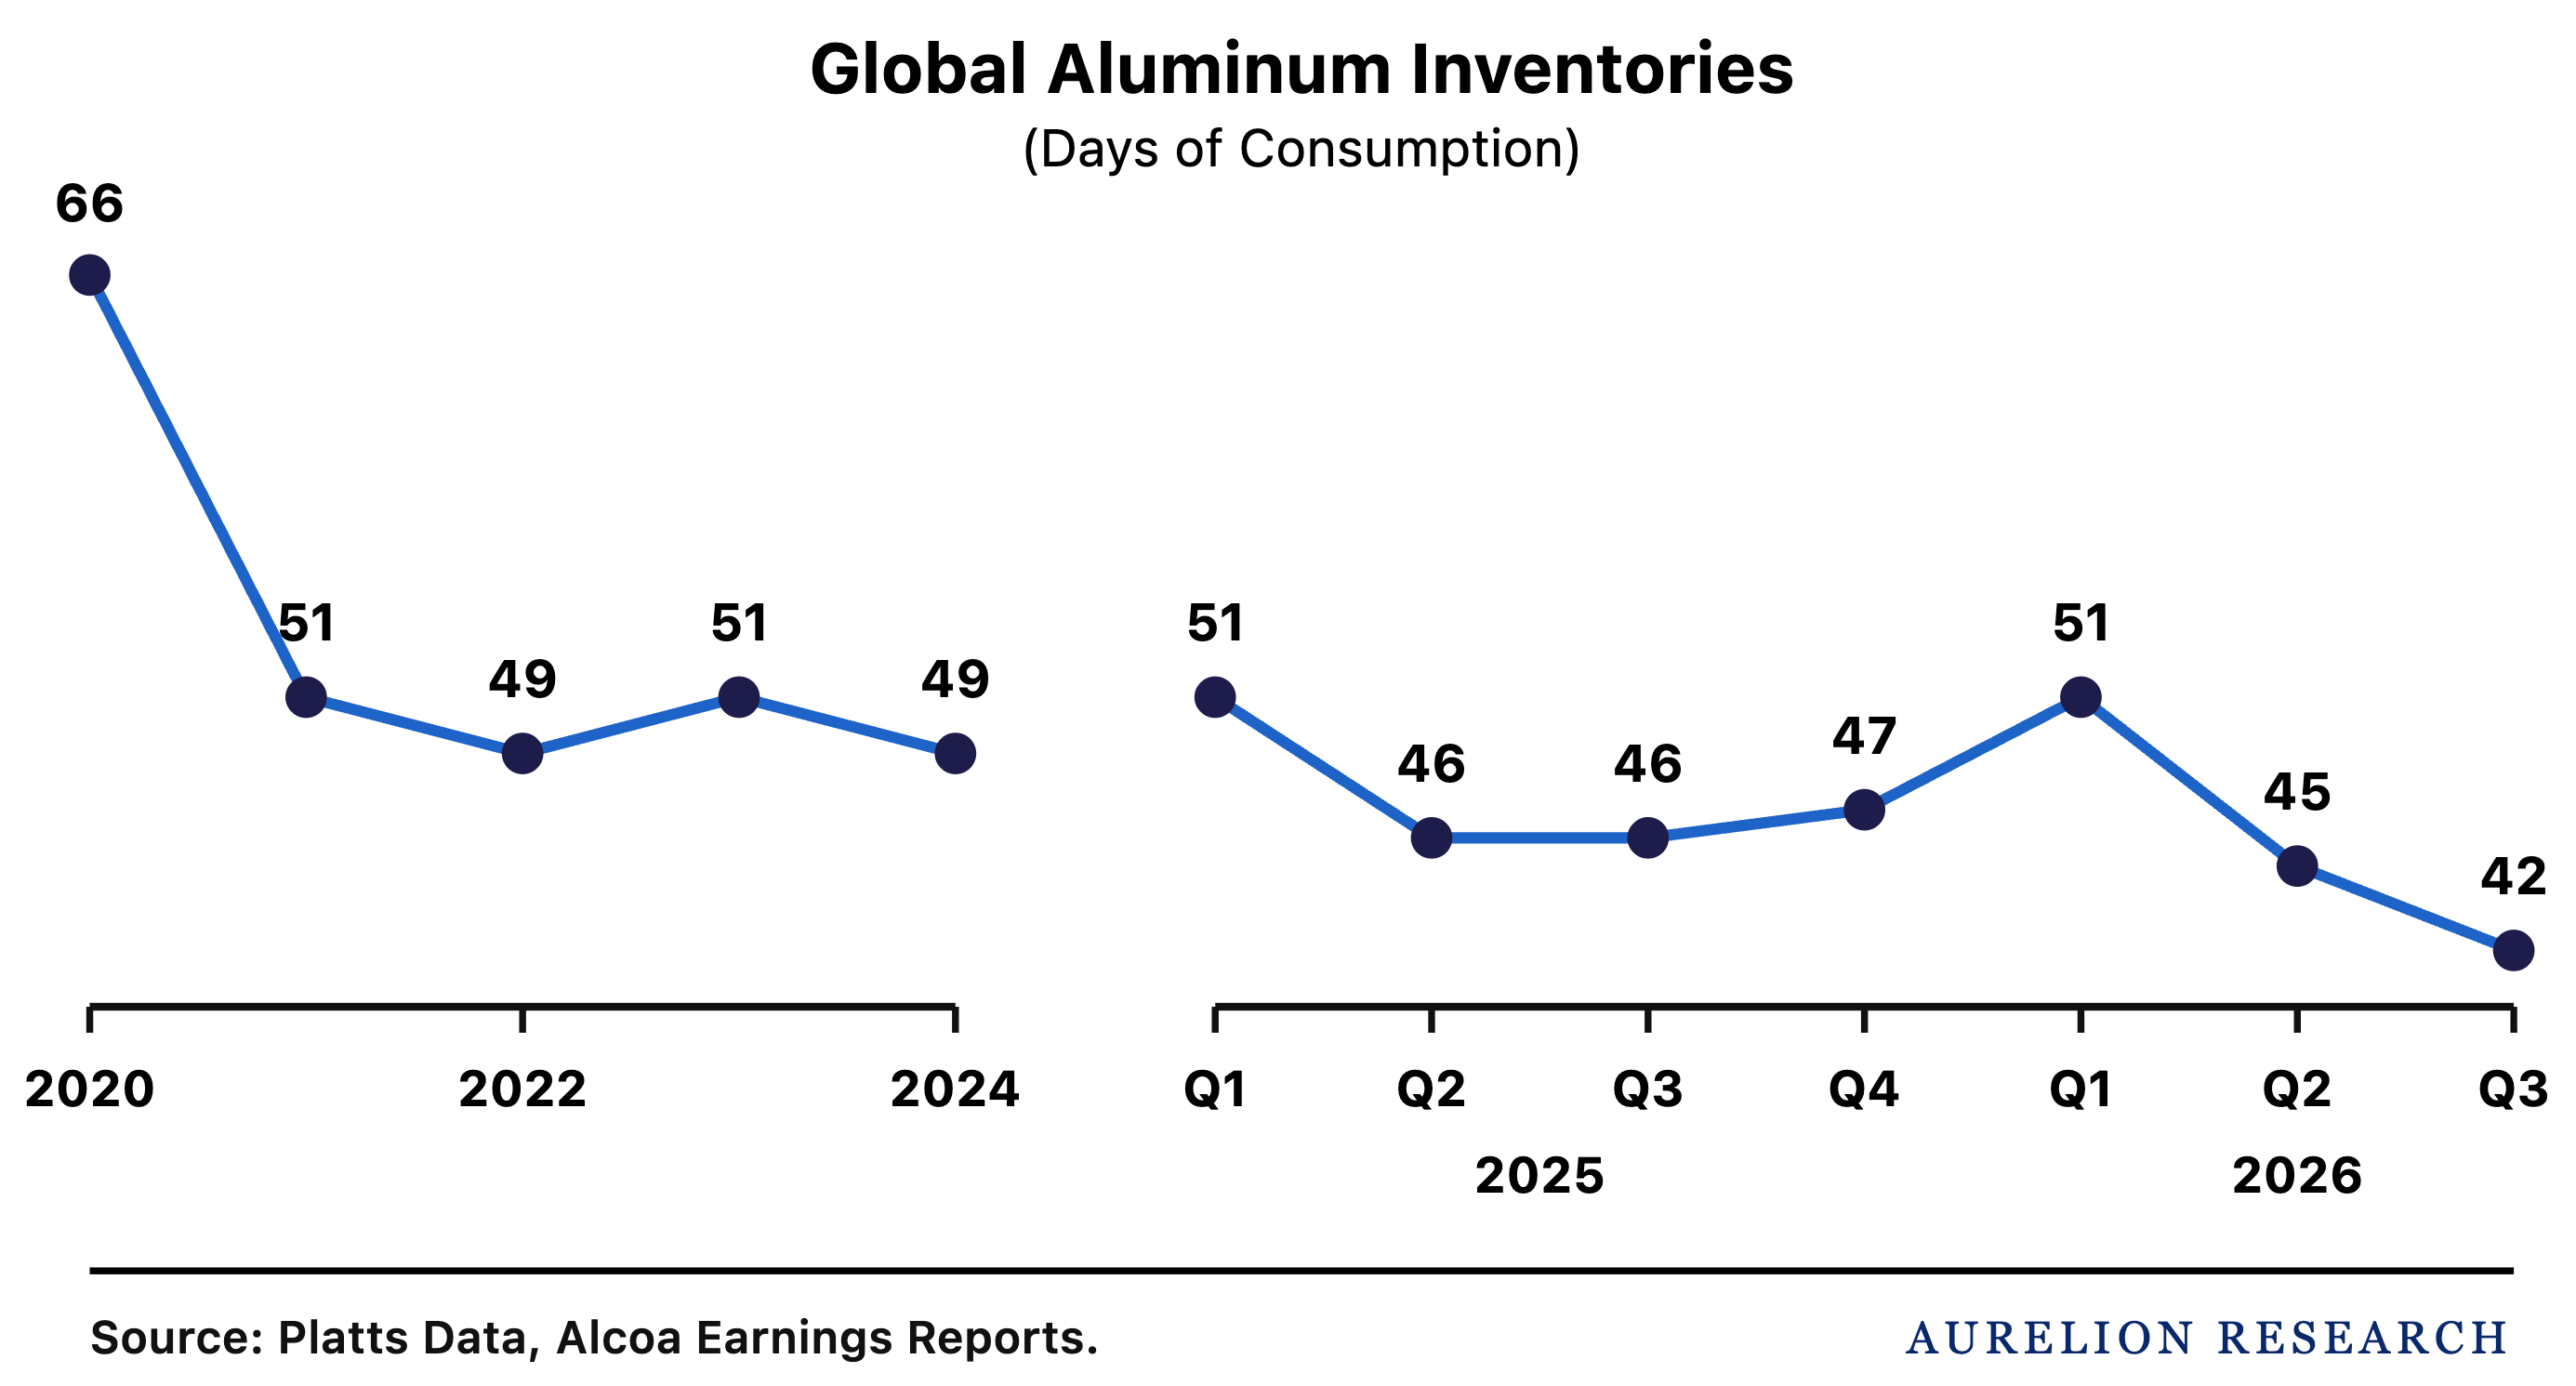
Since Q1 2026, aluminum inventories measured in days of consumption have continued to decline and are now near historic lows. With very little buffer in the market, further disruptions through the Strait of Hormuz could have a significant impact. Even as production recovers, it will take time for inventories to rebuild. We think the market is underestimating how long this could take.
The World Has Relied on China for New Aluminum Supply
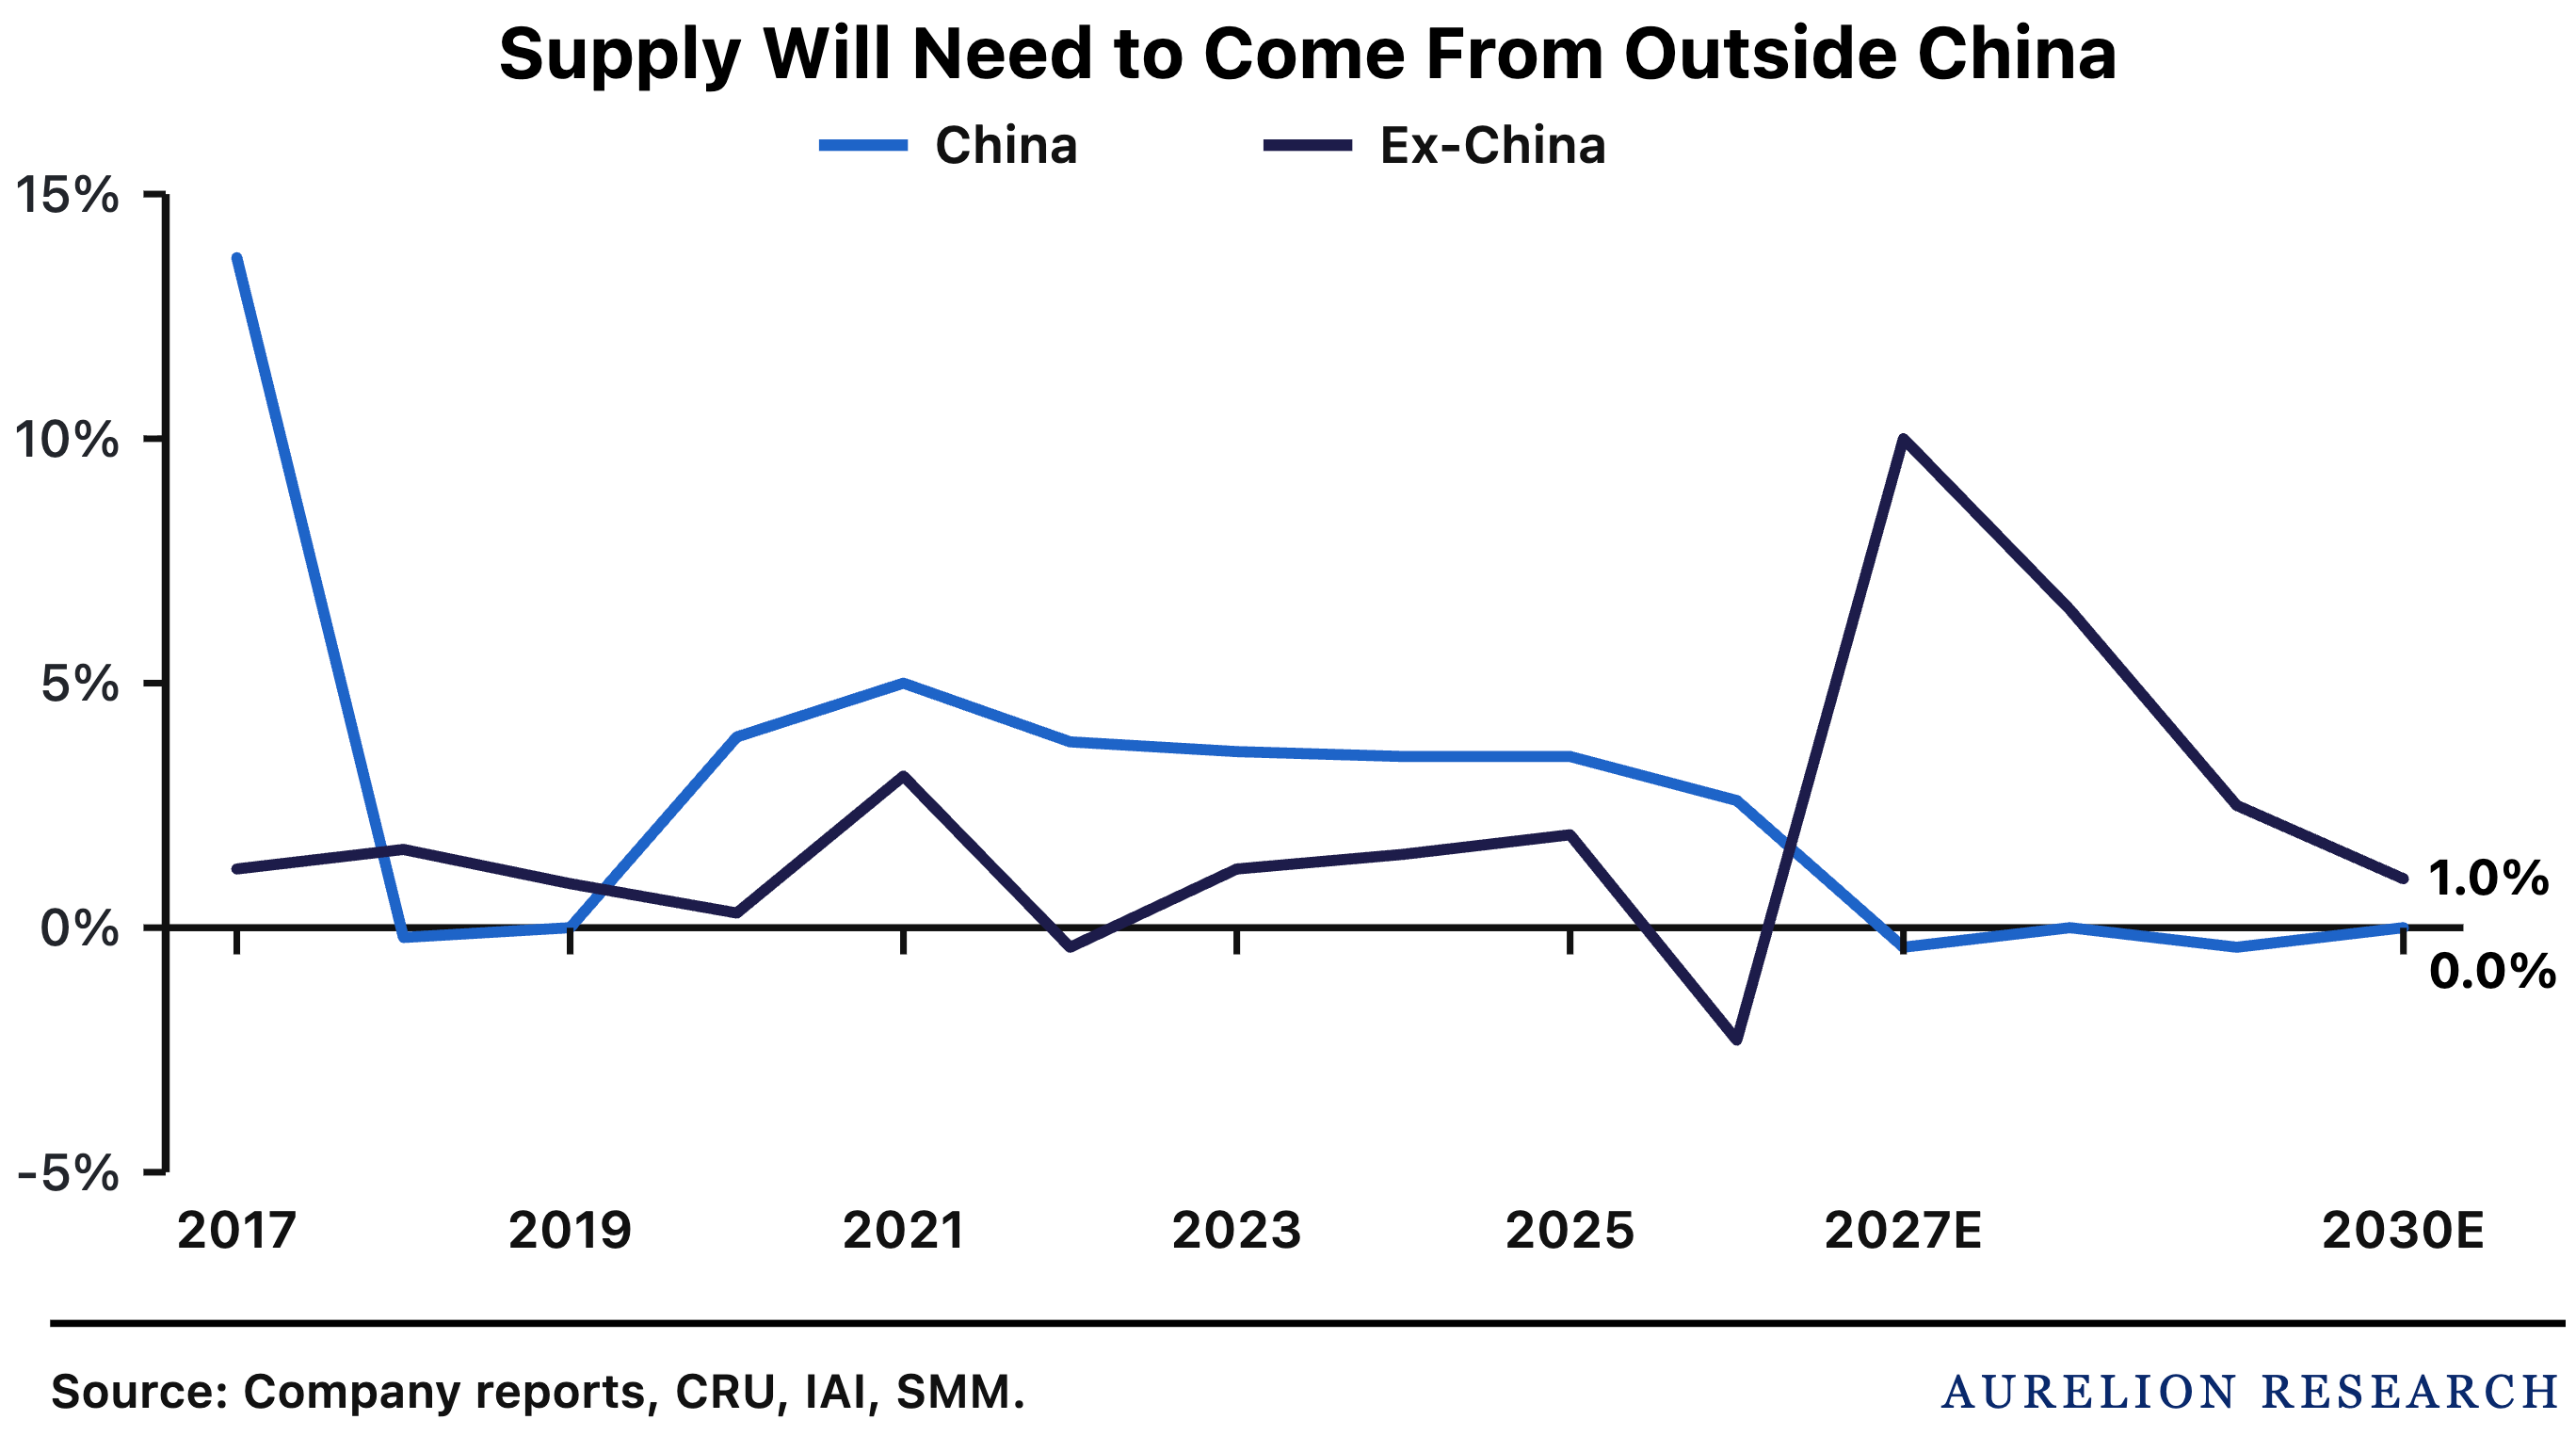
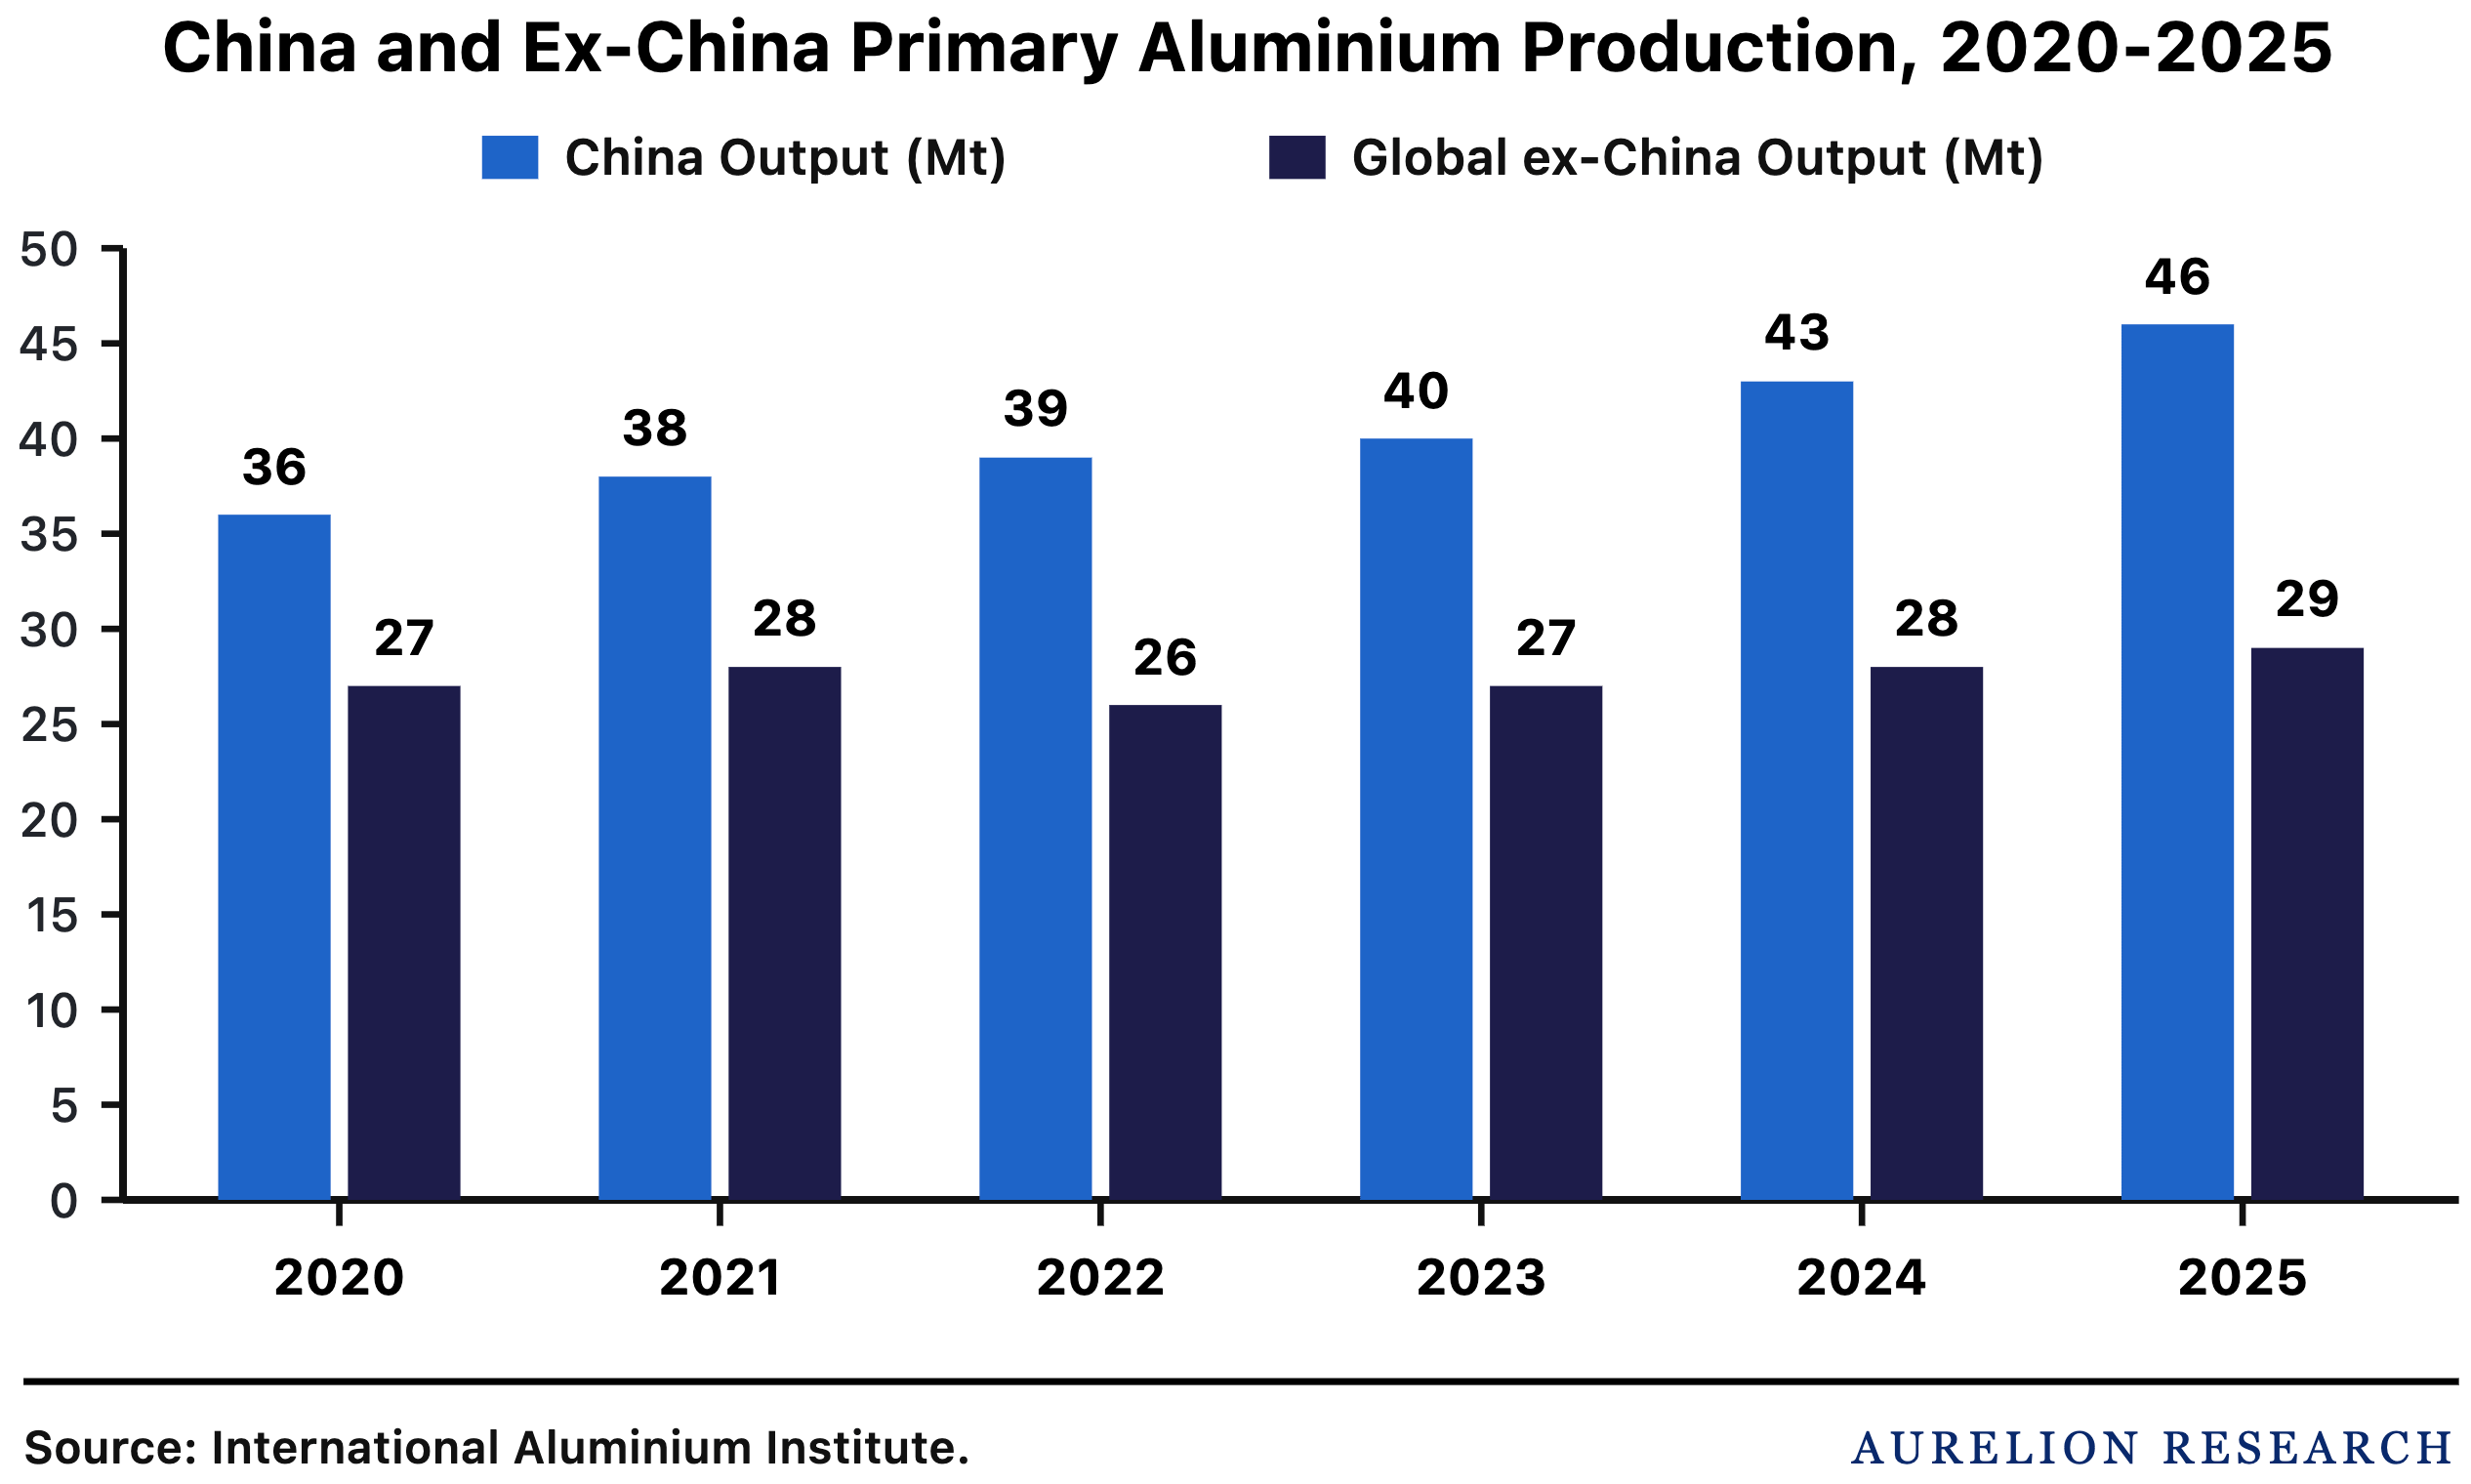
China has historically been the world’s main source of aluminum supply, accounting for nearly 60% of global primary aluminum production in 2025.
The Problem: China Has Little Room to Increase Production
China’s smelters are already operating near full capacity, leaving little room to increase production. Unlike in previous cycles, China will not be able to add millions of tons of new supply to the market. Future supply growth will therefore need to come from other countries, but they are not yet ready to fill the gap.
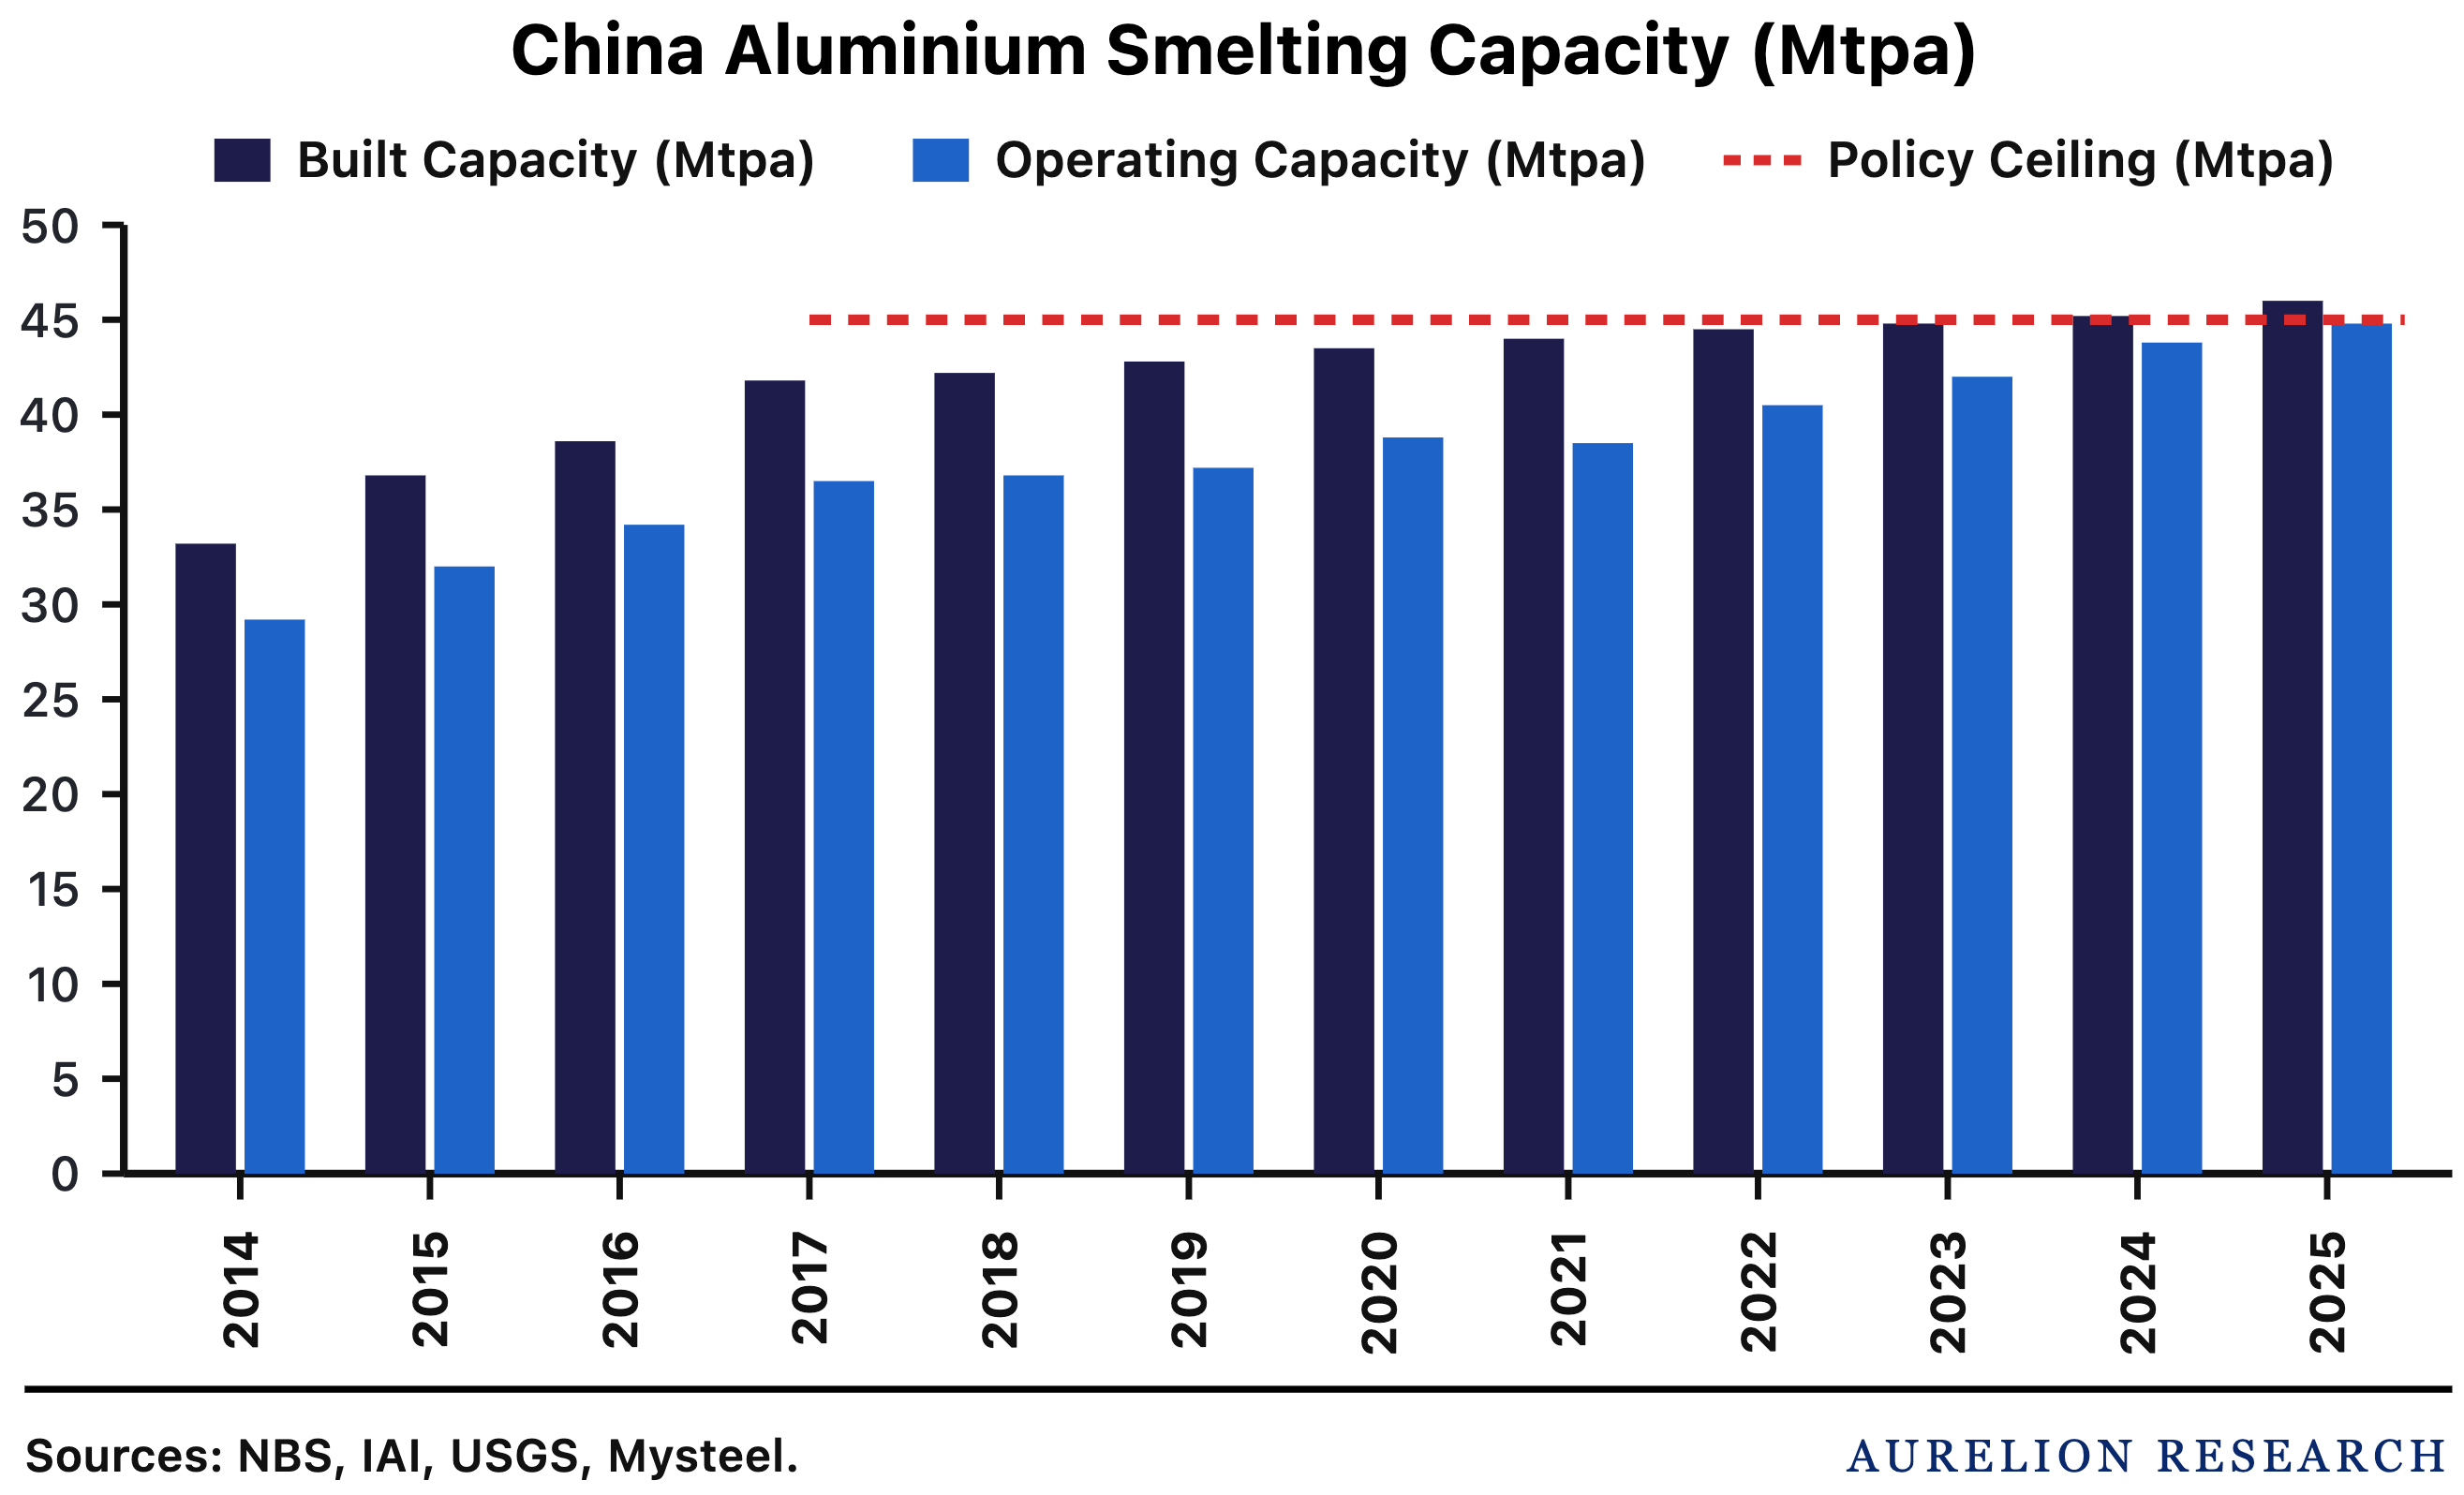
This is also why the U.S. is using tariffs and incentives to bring more aluminum production back home and reduce its reliance on foreign suppliers, particularly China. Trump recognized the risks of depending too heavily on foreign supply.
The Risk: Aluminum Market Balance Could Worsen Further
We think the market is underestimating aluminum demand growth, particularly in China, while being too optimistic about Indonesia’s and other countries’ ability to ramp up production. We have seen it last year in nickel, where Indonesia’s ambitious production targets have not always translated into actual output.
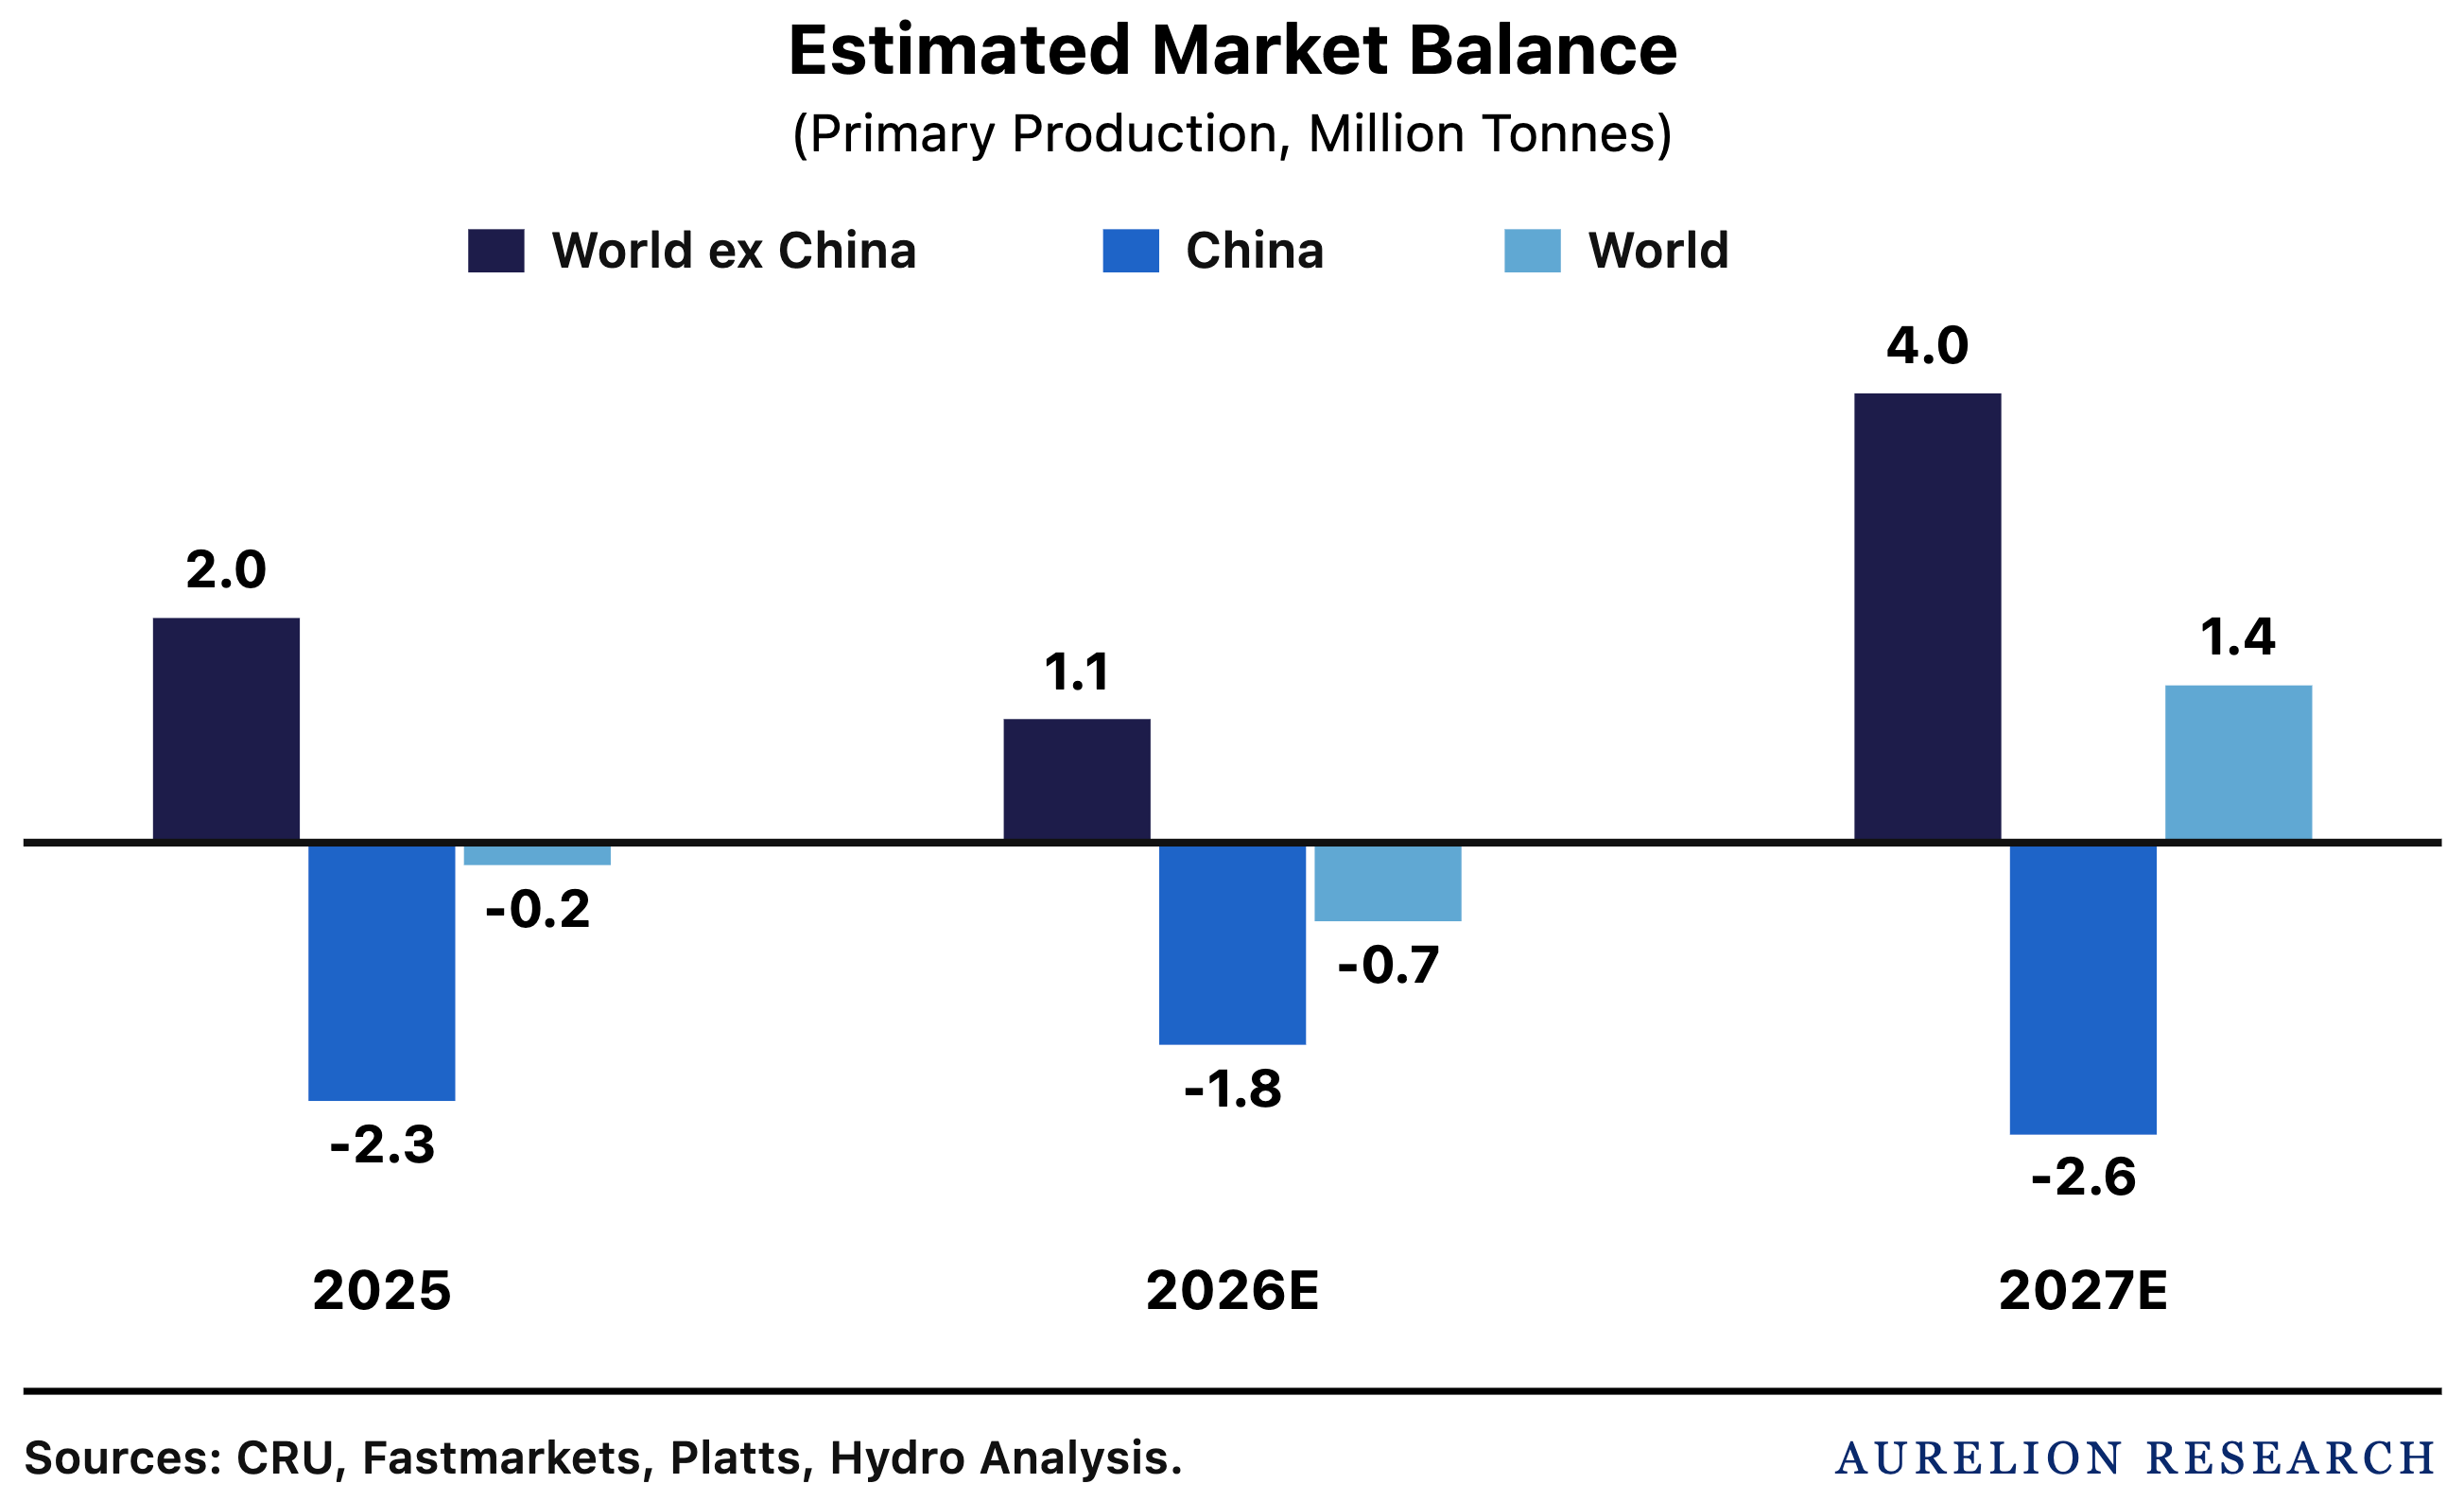
Indonesia Will Have a Hard Time Replacing Lost Supply
UBS’s commodity team is one of the more bearish voices on aluminum prices. Their view is that supply will remain sufficient, largely assuming that Middle Eastern production returns to normal levels. We are not counting on that happening anytime soon. We also find some contradiction in their outlook.
They see a 20% downside risk to Indonesia’s planned aluminum production additions, yet still expect enough new supply to meet market needs. So clearly, their bearish outlook relies on a very optimistic assumption that Middle Eastern production will recover much faster than we think it will.
Our take: We think Indonesia will struggle to meet its ambitious production targets, especially if Middle Eastern supply takes longer to recover.
New Aluminum Production Will Need to Come From the U.S.
Supply will need to come from outside China, which will greatly benefit U.S. producers. We see CENX as one of the best positioned to benefit from this.