

Cellebrite has not been a good performer, and to keep a position, we always ask ourselves: would we buy this stock again today?
We took the time to meet with Andrew Kramer, Treasurer and VP of Investor Relations. That helped us understand what the opportunity looks like today, what the large shareholders are doing, and how management thinks about growth.
While our entry point was wrong, we like the stock at current levels and would buy it today if we did not already own it. We view the valuation as very attractive relative to the quality and growth of the company.
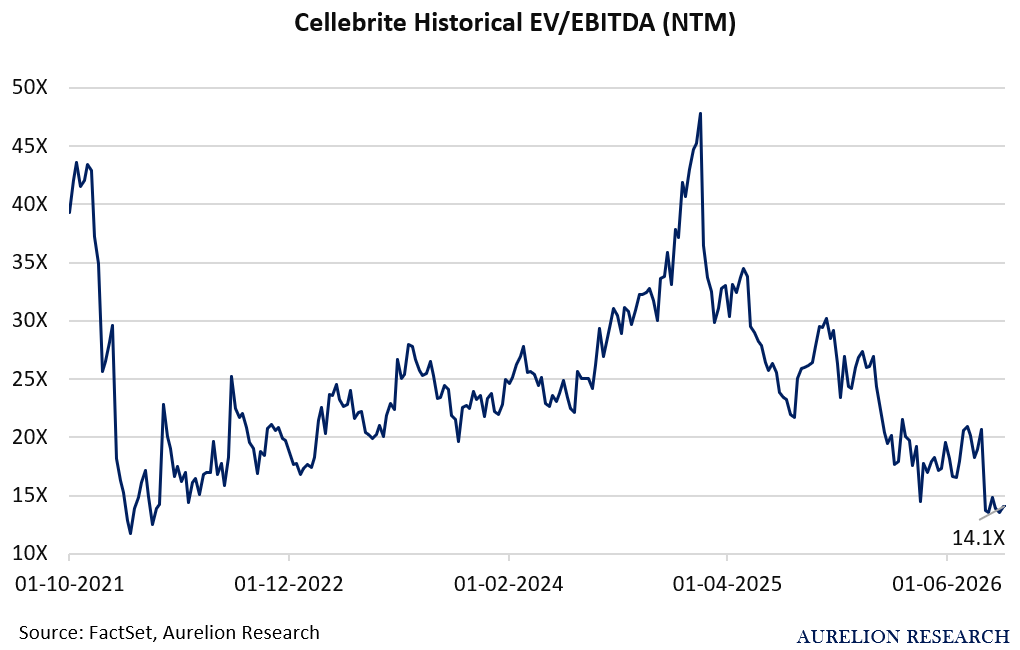
Note that Cellebrite generates a significant amount of cash flow, converting more than 110% of EBITDA into free cash flow, driven by favorable working capital.
That means the company trades at only 12.5x the free cash flow it generates. This type of multiple is usually reserved for highly capital-intensive companies or businesses with little to no growth.
Despite the recent reset in expectations, we view Cellebrite as a high-quality company that can grow earnings by 15% or more for several years. The new guidance framework and execution over the next quarter could provide the foundation for a strong turnaround.
Table of Contents
Company & Thesis Recap
Q2 2026 Earnings
The Point on SaaS
Potential Acquisition Target
Our Discussion with Cellebrite
The Road Ahead